

Deferit: Split Bills, Pay in 4
by Deferit
4.6
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.6
- Price
- Free
- Download
- 1.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
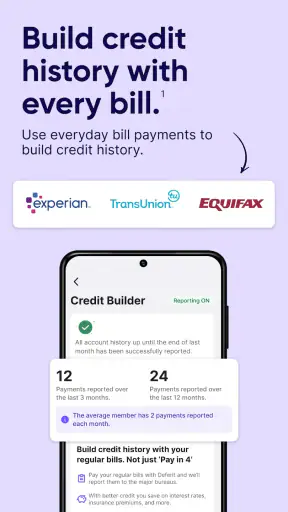
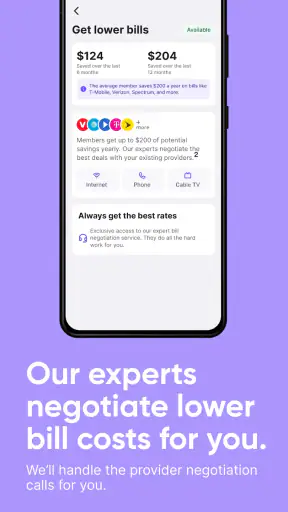
 Analysis by Getfullapps
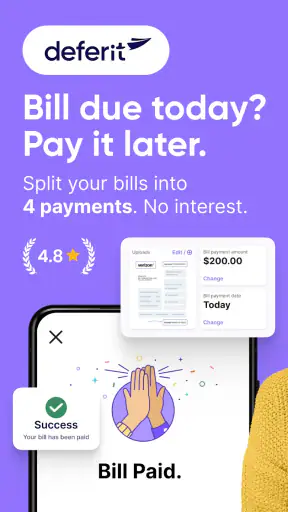
When a bill lands at the wrong moment, the problem is often timing rather than the total amount. Deferit: Split Bills, Pay in 4 is built around that situation. It is a finance app from Deferit that lets eligible users divide bills into four smaller payments without interest, instead of paying the full amount at once. I found the idea easy to understand, but the real value depends on using it as a short-term budgeting tool rather than treating it as extra income.
The app is free to install and aimed at everyone, which makes the first step feel less intimidating than opening a traditional credit product. It has reached over one million installs and holds a 4.6 average from around twenty thousand ratings, so it is clearly being used by a substantial audience. Those figures do not replace careful reading inside the app, though. Splitting a bill changes the payment schedule; it does not make the bill disappear.
What to expect before you split a bill
My first impression is that Deferit is most useful for predictable household expenses: a utility bill, phone account, internet service, insurance payment, or another regular charge that is already part of your budget. The important distinction is between smoothing cash flow and borrowing for an impulse purchase. If I know money is arriving soon but a bill is due before then, four scheduled payments can make the week easier to manage. If I am already struggling to cover several commitments, adding another schedule may simply move the pressure forward.
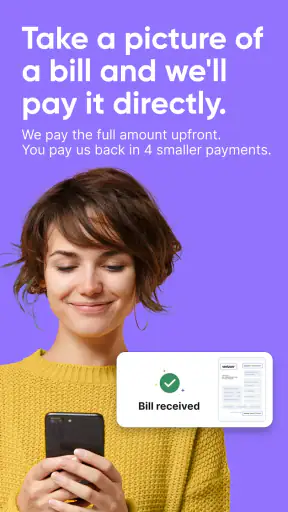
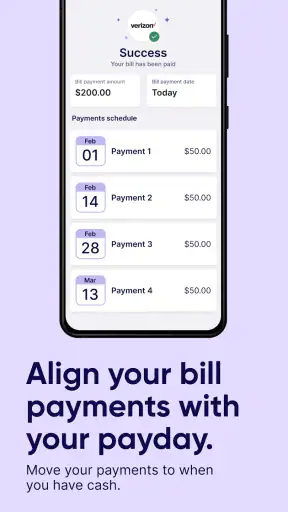
The central promise is straightforward: choose a bill, arrange it through the app, and repay it in four smaller portions with no interest. That sounds simple, but I would still approach the process as a commitment. Before confirming anything, I would check the amount, the due dates shown in the app, and the payment method being used. A split-payment service is only helpful when the later instalments fit alongside rent, food, transport, and existing subscriptions.
It is also worth understanding what this app is not. It is not a replacement for a bank account, a complete budgeting system, or a way to reduce the underlying cost of a bill. The service focuses on payment timing. Compared with paying a provider directly, it adds an extra layer to monitor. Compared with a conventional credit card, its appeal is the defined four-part structure and no-interest approach, but a card may be more flexible for someone who already manages a balance responsibly. For someone who wants to avoid revolving debt, the fixed split can be easier to understand.
The current version is 3.0.6, and the app supports Android devices running Android 7.0 or later. On iOS or Android, I would keep the operating system updated before starting, not because the concept is complicated, but because financial apps are better used on a device that receives current security updates. The age rating is Everyone, yet the financial decision itself still calls for adult judgement and a clear household budget.
Who will get the most from it
I think the strongest match is someone with regular income and an occasional mismatch between payday and bill dates. For example, imagine a phone bill arriving just before payday after an unusually expensive week. Instead of emptying the account immediately, the person could use the four-payment arrangement and reserve the remaining money for groceries and transport. The approach works best when the next payments are already accounted for, not when the user hopes future money will somehow appear.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
It can also suit people who prefer visible, separate commitments. A normal card statement may combine groceries, entertainment, fuel, and bills into one balance. A four-part schedule gives the bill its own repayment path, which can make the obligation easier to identify. I would still write the future payment dates in my calendar or budget, because relying only on memory is an avoidable mistake.
I would be more cautious if your income changes from week to week, if several bills are already overdue, or if you often forget automatic payments. In those cases, a conversation with the bill provider about a payment arrangement may be better. A free budgeting app may also be more appropriate if the real problem is not one difficult bill but a lack of visibility across all spending.
Getting from installation to the first useful payment
I’d treat the first setup as a chance to learn the payment flow, not as a reason to move several bills at once. Starting with one familiar expense makes it easier to compare the app’s schedule with your own calendar and spot any mismatch before it affects your monthly budget. Once that process is clear, the next section looks at how to make the first arrangement genuinely useful.
Start with one ordinary bill
For a first attempt, I would not begin with the largest or most urgent bill in the household. I would choose one familiar expense whose amount and due date I understand. That makes it easier to see how the process works without adding confusion. Have the bill details available, and make sure the name and amount match what you expect before moving ahead.
The initial setup should be treated like a financial application rather than a casual shopping app. Follow the identity and account instructions shown on screen, review the repayment information, and use payment details that you control. I would avoid rushing through the screens simply because the service is presented in a friendly way. The key question at every stage is: “Can I comfortably make each of the four payments when scheduled?”
One practical tip is to prepare a small cash-flow snapshot before opening the app. Note the bill amount, the money currently available, the next income date, and other payments due before then. This takes only a minute, but it prevents the common mistake of looking at the first smaller payment while ignoring the remaining three. The first payment is not the affordability test; the complete schedule is.
Another useful habit is to keep the original bill accessible after arranging it. I would save the provider name, account reference, and due-date information somewhere secure, then compare the completed arrangement with the original notice. This is especially helpful when several bills have similar names. The app can organize the payment process, but only you can confirm that the correct account is being handled.
The first successful action
A meaningful first success is not merely installing the app or opening an account. It is completing one bill arrangement and knowing exactly what happens next. Once the bill is accepted and the schedule is visible, I would check three things: the total being handled, the date and amount of the next payment, and where future payments will be taken from. If those details are clear, the app has already done its main job for that moment.
I would then set reminders outside the app as a backup. A calendar alert a day or two before each scheduled payment gives me time to move money or notice a problem. This is one of the less obvious trade-offs: the smaller instalments may feel manageable, but they create several dates to remember instead of one. For organized users, that can be convenient. For forgetful users, it can become an administrative burden.
After the first arrangement, I would wait before adding more bills. Using one schedule lets you observe how it fits with normal spending. It also shows whether the app’s workflow feels comfortable on your device and whether you understand the status information. Adding multiple commitments immediately can make a tidy-looking dashboard hide a crowded future budget.
There is a psychological benefit to separating a large payment into smaller planned steps, but that benefit can work against you if it makes a bill seem cheaper than it is. I found it more responsible to think of the full amount first and the four payments second. The split is a timing mechanism, not a discount. Keeping that order of thought helps prevent overuse.
Where first-time users may hesitate
The phrase “pay in four” can cause confusion because users may assume every bill, every provider, or every situation follows exactly the same process. I would read the specific terms and schedule presented for the bill on screen rather than relying on a general expectation. The app’s basic idea is consistent, but the details that matter to your transaction are the ones displayed during setup.
Another point that deserves attention is the difference between a bill being submitted and the repayment plan being fully understood. Do not close the app as soon as you see a confirmation message. Review the transaction status and keep any reference information available. If something looks different from the original bill, pause and resolve that mismatch before arranging another payment.
Some people may also wonder whether “no interest” means “no responsibility.” It does not. The attraction is that the split does not add interest, but scheduled payments still need to be made. I would never use the absence of interest as a reason to take on a bill that was unaffordable in full. The right comparison is not only with interest-bearing credit; it is also with paying on time through the provider’s normal channel.
There is a further practical trade-off when a user has many subscriptions. Deferit may help with one large bill, but using it repeatedly for small recurring charges could make the monthly picture harder to read. In that situation, canceling unused subscriptions, changing due dates where possible, or building a small bill buffer may produce a stronger long-term result. The app is better as a targeted tool than as an automatic answer to every payment.
How it compares with ordinary alternatives
Paying a provider directly remains the simplest option when the money is available. It has fewer moving parts, fewer dates to track, and no intermediary workflow. I would choose that route whenever paying in full would not affect essentials or emergency savings. Deferit becomes more interesting when the timing of the payment is the actual obstacle.
A provider’s own extension or hardship arrangement may be preferable when a bill is already difficult to afford. That conversation can address the underlying problem rather than merely dividing the amount. On the other hand, Deferit may feel more convenient for a routine short-term gap where the user expects to catch up soon and wants a structured schedule.
Credit cards and other borrowing options can offer broader spending flexibility, but that flexibility is also their danger. A defined four-payment plan can be easier to track than an open-ended balance. Still, a card may be the better fit for someone who needs a wider emergency facility and already understands interest, statements, and repayment discipline. I would not choose between them based only on the size of the first payment; I would compare the full obligations and the consequences of missing one.
Traditional budgeting apps solve a different problem. They help you see income, categories, and recurring expenses, while Deferit focuses on arranging a bill payment. Using both concepts together can make sense: one tool handles the immediate schedule and the other shows whether that schedule fits the month. If you only need awareness of spending, adding a bill-splitting service may be unnecessary.
Small habits that make the arrangement safer
My preferred workflow is to create a “future bills” note immediately after the first successful arrangement. I would record the bill name, the four scheduled dates, and the amount expected on each date. I would then compare those dates with payday and other automatic withdrawals. This exposes conflicts early, especially when several commitments fall in the same week.
I would also avoid judging affordability from the account balance on the day I arrange the bill. A balance can look healthy before rent, groceries, transport, and existing subscriptions leave the account. Looking ahead is more useful than looking at the present number. This is a simple but important insight because payment-splitting products can make the immediate transaction feel smaller while the household obligation remains unchanged.
For shared household bills, decide who is responsible before arranging anything. If two people normally contribute, the person using the app should not assume the other contribution will arrive without a clear agreement. The app can help schedule the payment, but it cannot resolve disagreements between family members or housemates. I would treat the repayment plan as my responsibility unless the arrangement is explicit.
Finally, keep the app limited to bills you can explain. If I cannot say what the bill is, why I am splitting it, and where the later payments will come from, I would stop. That rule prevents the service from becoming a way to postpone decisions. It also keeps the app’s strongest use case intact: handling a temporary timing problem with a known expense.
My view after using it as a budgeting aid
Deferit is a focused finance app, and that focus is its best quality. It does not need to replace every money tool in your phone. For the right user, dividing a bill into four interest-free payments can turn an awkward due date into a clearer plan. The free price and Everyone rating make it approachable, while the large install base and 4.6 average suggest that many users find the basic concept useful.
My reservation is that convenience can encourage repetition. One carefully planned split may solve a short-term mismatch. Several overlapping splits can create a second calendar of obligations that is harder to manage than the original bills. I would therefore start with one bill, confirm that the schedule fits real income, and only then decide whether another use is sensible.
The app is worth considering if you want a structured way to manage a temporary bill-timing problem and you are comfortable monitoring future payments. I would skip it if you need debt relief, have no reliable plan for the later instalments, or simply want a general spending tracker. In those situations, direct negotiation with the provider, a basic budget, or professional financial guidance may be a better next step.
For a first-time user, the reassuring path is simple: install it, choose one familiar bill, read every schedule detail, complete the arrangement, and place the future payments in your budget immediately. If the numbers still work after that reality check, Deferit can be a useful bridge between an inconvenient due date and a manageable payment plan. I would use it deliberately, not automatically, and judge its success by whether it makes the whole month clearer rather than merely making today cheaper.
Pros
- Splits eligible bills into manageable scheduled payments.
- Payment reminders help reduce the risk of missing due dates.
- Supports budgeting by showing upcoming installment amounts.
- Can help cover essential expenses during temporary cash shortages.
- Simple interface makes bill tracking easy for new users.
Cons
- Not every bill or provider may be supported by the service.
- Late payments may lead to fees, restrictions, or account consequences.
- Approval and spending limits can vary between users.
- Installments may encourage spending beyond your regular budget.
- Service availability and features may differ by country.
FAQs for Deferit: Split Bills, Pay in 4
What is Deferit: Split Bills, Pay in 4?
Deferit is a financial app designed to help users manage certain bills and everyday payments. Depending on eligibility and location, it may allow you to pay a bill through the app and repay Deferit over scheduled installments. It can also include bill-splitting or pay-in-four features, making larger expenses easier to spread across several payments instead of paying everything at once.
How does Deferit’s bill-splitting or Pay in 4 feature work?
After creating an account, you generally enter the bill details or select an eligible purchase, then review the proposed payment schedule before confirming. Deferit may cover the payment according to its approval process, while you repay the amount in installments. Read the schedule carefully, because fees, limits, repayment dates, and available features can vary by user, merchant, and country.
Are there fees or interest charges when using Deferit?
Deferit’s costs depend on the specific service you use, your membership or account type, and the payment arrangement offered to you. Some plans may include subscription charges, transaction fees, late fees, or other costs, while certain options may be advertised as interest-free. Before accepting a payment plan, check the complete fee summary and understand the consequences of missed or delayed payments.
Who can use Deferit, and what information is required to sign up?
Eligibility is not automatic and may depend on your age, country or region, identity verification, payment method, account history, and other approval criteria. During registration, the app may request personal details, contact information, and bank or card information so it can verify your identity and process repayments. Availability and requirements can change, so confirm the current terms in the app.
What happens if I miss a Deferit repayment?
Missing a scheduled repayment can lead to additional fees, restricted access to future payment plans, or other consequences described in Deferit’s agreement. Automatic payments may be attempted using your linked payment method, so maintaining sufficient funds is important. If you expect a problem, contact Deferit support as soon as possible and review the hardship or repayment options that may be available.

Deferit: Split Bills, Pay in 4
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via contact@deferit.com, visit https://deferit.com/, or review their https://deferit.com/privacy/.










